Q3 results and Antamina stream purchase
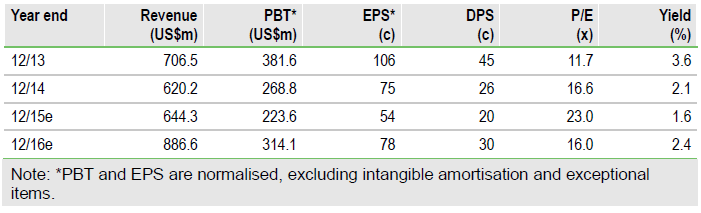
Excluding a US$154.0m impairment charge relating to its 777-mine gold stream beyond 2020 (which was in any case omitted from our long-term forecasts), Silver Wheaton’s (N:SLW) Q315 results were closely in line with our expectations. PBT was 3.5% higher than our forecast; PAT was 2.6% lower due to a higher than expected tax charge. More significantly, SLW has acquired a new silver stream from the world-class Antamina copper mine in Peru that has caused us to increase both our earnings forecasts and valuation.
Operations
Operationally, SLW posted both production and sales records in Q315, driven by production records at Salobo and Penasquito and a sales record at San Dimas. Sales at San Dimas in particular reversed the build-up of inventory in Q215, but were largely offset by under-sales at Yauliyacu and elsewhere. Gold production was lower at Sudbury (owing to planned maintenance), but higher than expected at both Constancia and Minto. The ramp-up of production at Salobo was weaker than expected in July and August, which resulted in an under-sale of gold during the quarter and consequently only a 1.6% decrease in payable ounces produced but not yet delivered overall, to 6.3Moz AgE.
To Read the Entire Report Please Click on the pdf File Below


